


Along with most other refiners, Phillips 66 set a company record for adjusted and unadjusted earnings per share, net income and EBITDA in Q3 2026, the company said during its quarterly earnings call.
Crude inputs averaged 1.961 MMb/d, up from 1.919 MMb/d in Q2, while total processed inputs (including purchased intermediates) increased from 2.053 MMb/d to 2.132 MMb/d. Utilization reached 98%, versus 96% sequentially and 99% a year earlier. Year-over-year volume comparisons require care because Phillips acquired the remaining 50% of Wood River and Borger from Cenovus in October 2025, and the Los Angeles refinery ceased operations in Q4 2025.
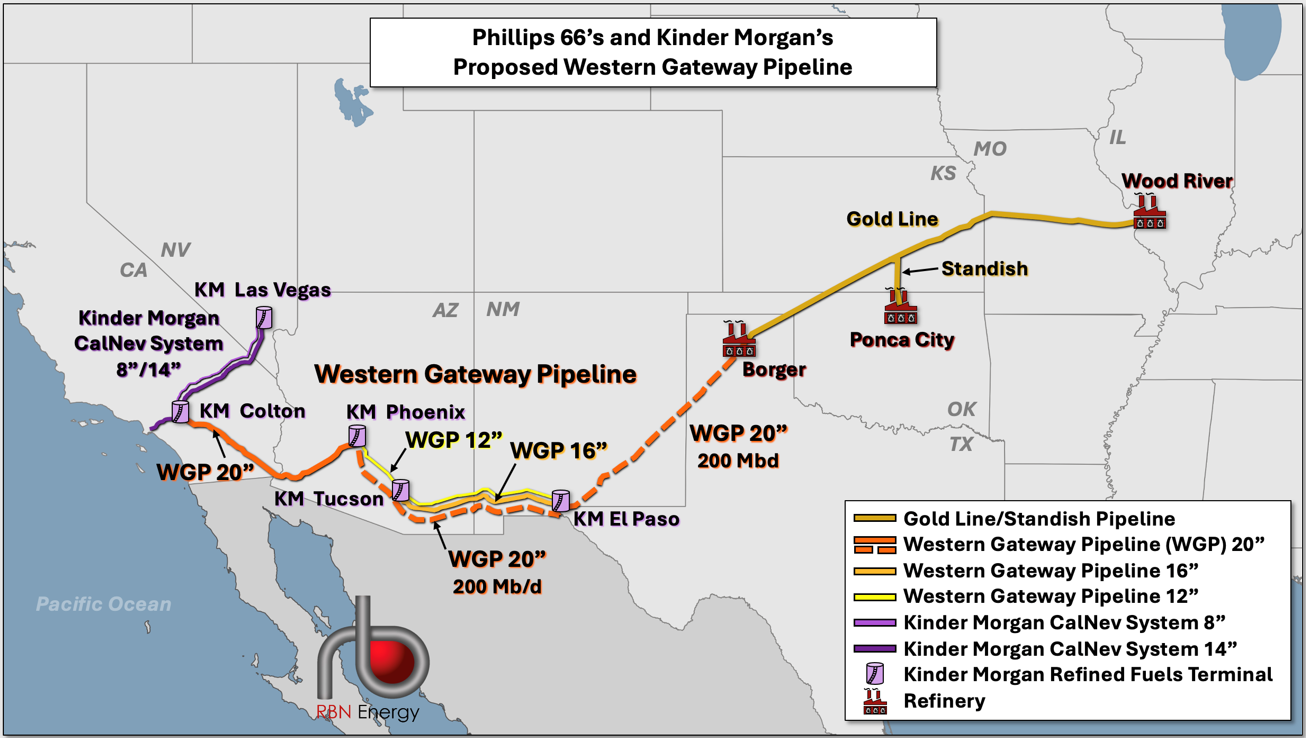
P66, Kinder Morgan and HF Sinclair reached a final investment decision (FID) on their Western Gateway project (see map below) during Q3 as well. The approximately $5 billion pipeline system, targeting completion in 2029, would initially provide 230 Mb/d of capacity to move refined products from the Midcontinent and Gulf Coast regions to Arizona, Southern California and Southern Nevada. It combines a new Borger-Phoenix pipeline with reversals of existing infrastructure, including the P66 Gold line, which currently flows east from Borger, TX, to Cahokia, IL, in the St. Louis metro area and adjacent to the Wood River refinery.
Outside of refining, P66 continues to invest in its integrated Permian-to-Gulf Coast NGL system. Its investment program includes the Iron Mesa and Zeus processing plants (each 300 MMcf/d capacity) in the Permian Basin and another Corpus Christi fractionator with a capacity of 100 Mb/d, bringing P66’s total fractionation capacity there to 270 Mb/d. The Coastal Bend (formerly EPIC NGL) pipeline expansion is expected to begin moving initial volumes in Q4 2026 and reach 350 Mb/d in early 2027, up from 225 Mb/d today.
Management remained bullish on refining margins despite softer product demand. They estimated U.S. gasoline demand was down ~2.5% and U.S. diesel demand was down ~1.5%, though they did not specify the comparison period or basis. It also citied approximately 7 MMb/d of refining capacity offline across Russia, Asia and the Middle East. Elevated refining margins are expected persist through much of 2027, along with higher freight costs, making previously secured time charters a competitive advantage for P66 in the near term.
Finally, CPChem’s Ras Laffan and Golden Triangle Polymers projects are targeting full operations in 2027. Each complex includes a 2.08 million MT/year ethane steam cracker, located in Qatar and Orange, TX, respectively. The last major U.S. steam cracker to start up was Shell’s 1.5 million MT/year Monaca, PA, facility, which began operation in November 2022.
