


As discussed in this week’s Crude Billboard, the cost of moving U.S. crude into international markets became a more significant constraint last week, as the broader energy market strengthened amid escalating geopolitical tensions. The cost to charter an Aframax vessel from the U.S. Gulf Coast (USGC) to Europe (green line in chart below) more than doubled, rising from below 250 Worldscale (WS) points at the end of the prior week to nearly WS500 on Friday, their highest level since early April. The increase was not limited to a single vessel class or destination but reflected broader tightening across the tanker market.
A raise in rates also proved consequential for long-haul exports. The cost of chartering a Very Large Crude Carrier (VLCC) from the USGC to Asia soared 25% to nearly $37 million per voyage on Friday, the highest since RBN’s records began and almost four times the year-ago level, before skyrocketing to a new record high of $44.8 million per voyage on Monday (far right of blue line in chart below).
These increases materially change the export calculation. A wider Brent-WTI spread generally improves the economics of moving discounted U.S. barrels overseas, but the spread must now cover a substantially larger freight bill before an exporter realizes any improvement in netback. Unless the Brent-WTI spread widened by enough to offset the weekly increase in VLCC costs, the economics of an incremental cargo to Asia deteriorated despite the more supportive benchmark differential.
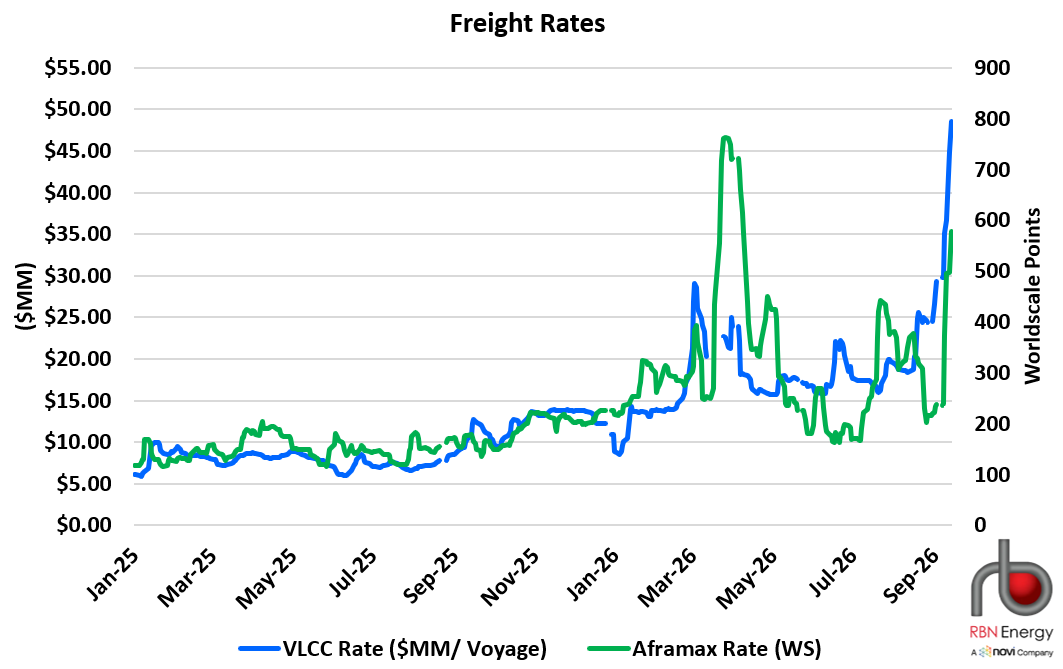
Source: Bloomberg
