

EQT started off the week by announcing that it would regain its title as the country’s largest natural gas producer by purchasing Range Resources. We covered that announcement and its implications in our blog Roar. As EQT held the transaction call for the merger on Monday, it cancelled its planned earnings call on Tuesday. However, it did release the earnings report and presentation on time. The presentation gives an overview of how EQT sees some elements of the gas market evolving over time.
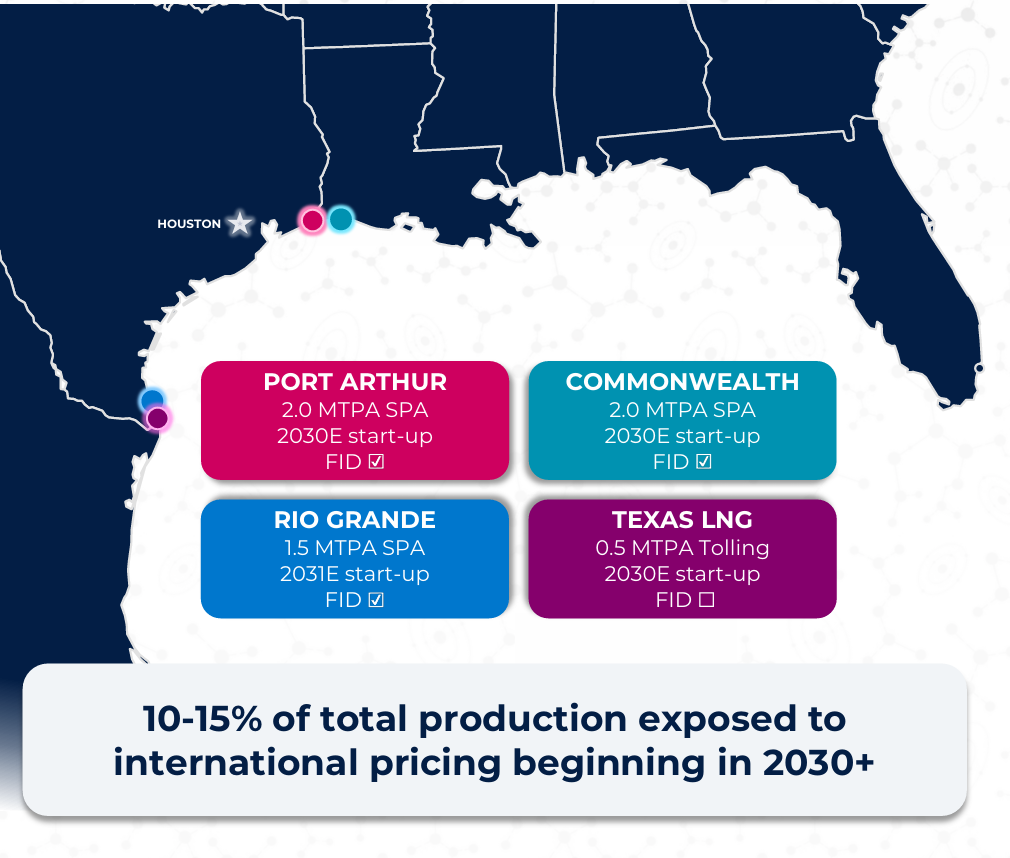
Source: EQT
Notably, the presentation clarifies that the 24 Bcf/d of potential Appalachian demand growth over the coming decade that it touted in the Range Resources announcement is “underpinned by power, data center and egress.” The egress portion specifically implies that not all of this new demand is going to come from near the basin, but from new pipelines leading outbound. And the company is increasing its exposure even further afield. As seen in the graphic above, it has 6 mtpa (0.8 Bcf/d) in contracted capacity at four LNG facilities, three of which have reached FID. Two of these facilities are so far south in Texas that access to any actual Appalachian molecules is impossible. However, it gives the company exposure to global prices. EQT notes in the presentation that it has more price exposure to global LNG than any of its six closest peers as independent oil and gas producers.