


We are reaching the time of year when the Northeast typically starts getting chilly, but the weather has been mild so far in October. The already low Appalachian cash basis prices have plunged even lower in response. Full cash prices have been punishingly low for the production zone over the week ended October 13, averaging about 85 cents for EGS and 83 cents for TGP Z4 according to Bloomberg data — far below breakevens for even the most well-situated producer. Unlike the futures market, physical trading was closed for Monday’s Columbus Day holiday. That means that cash prices for five of the seven days last week were determined in trading on Friday for Saturday-through-Tuesday delivery.
Source: RBN NATGAS Appalachia, Wood Mackenzie
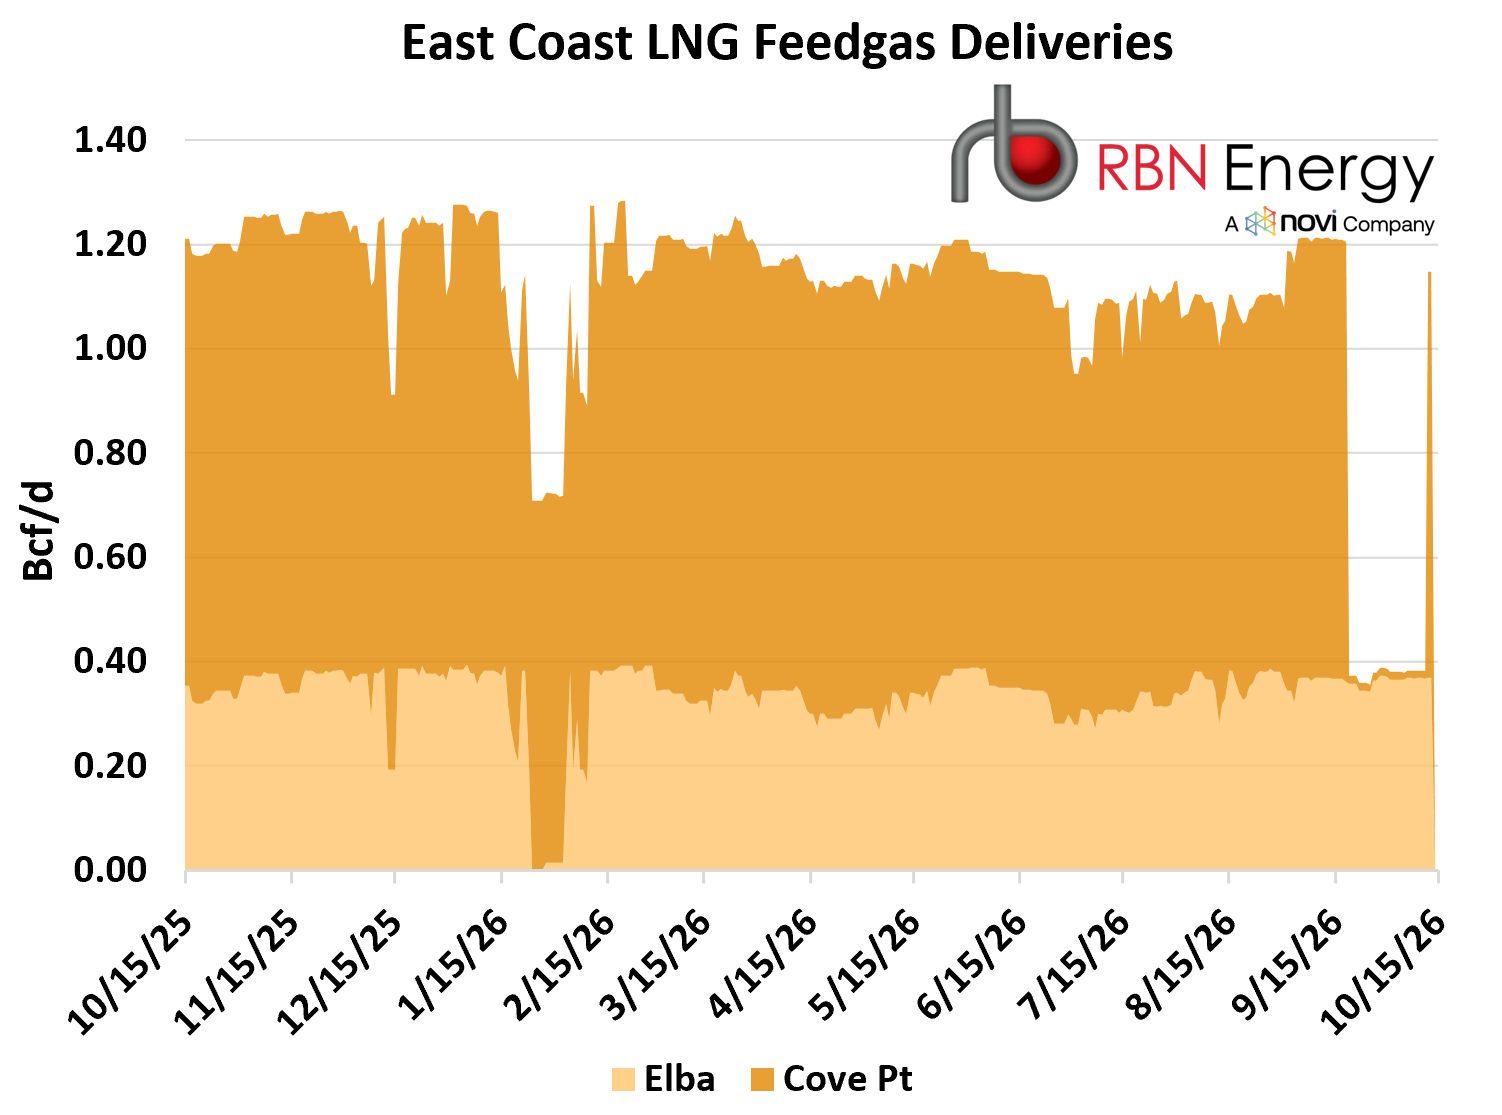
Overall Northeast demand averaged 13.7 Bcf/d during the week ended October 13, down 0.5 Bcf/d week on week. Regional demand, excluding LNG feedgas, was 13.5 Bcf/d, down 0.3 Bcf/d from last year and 0.5 Bcf/d lower than the 5-year average. Power demand decreased by 1 Bcf/d but Res/Comm demand grew by 0.2 Bcf/d and Industrial demand moved up by 0.1 Bcf/d. LNG feedgas at Cove Point made its return on Monday, completing a three-week maintenance outage. The facility goes down for a maintenance of similar length every year, but is back to normal as seen in the dark orange section of the graph above.
