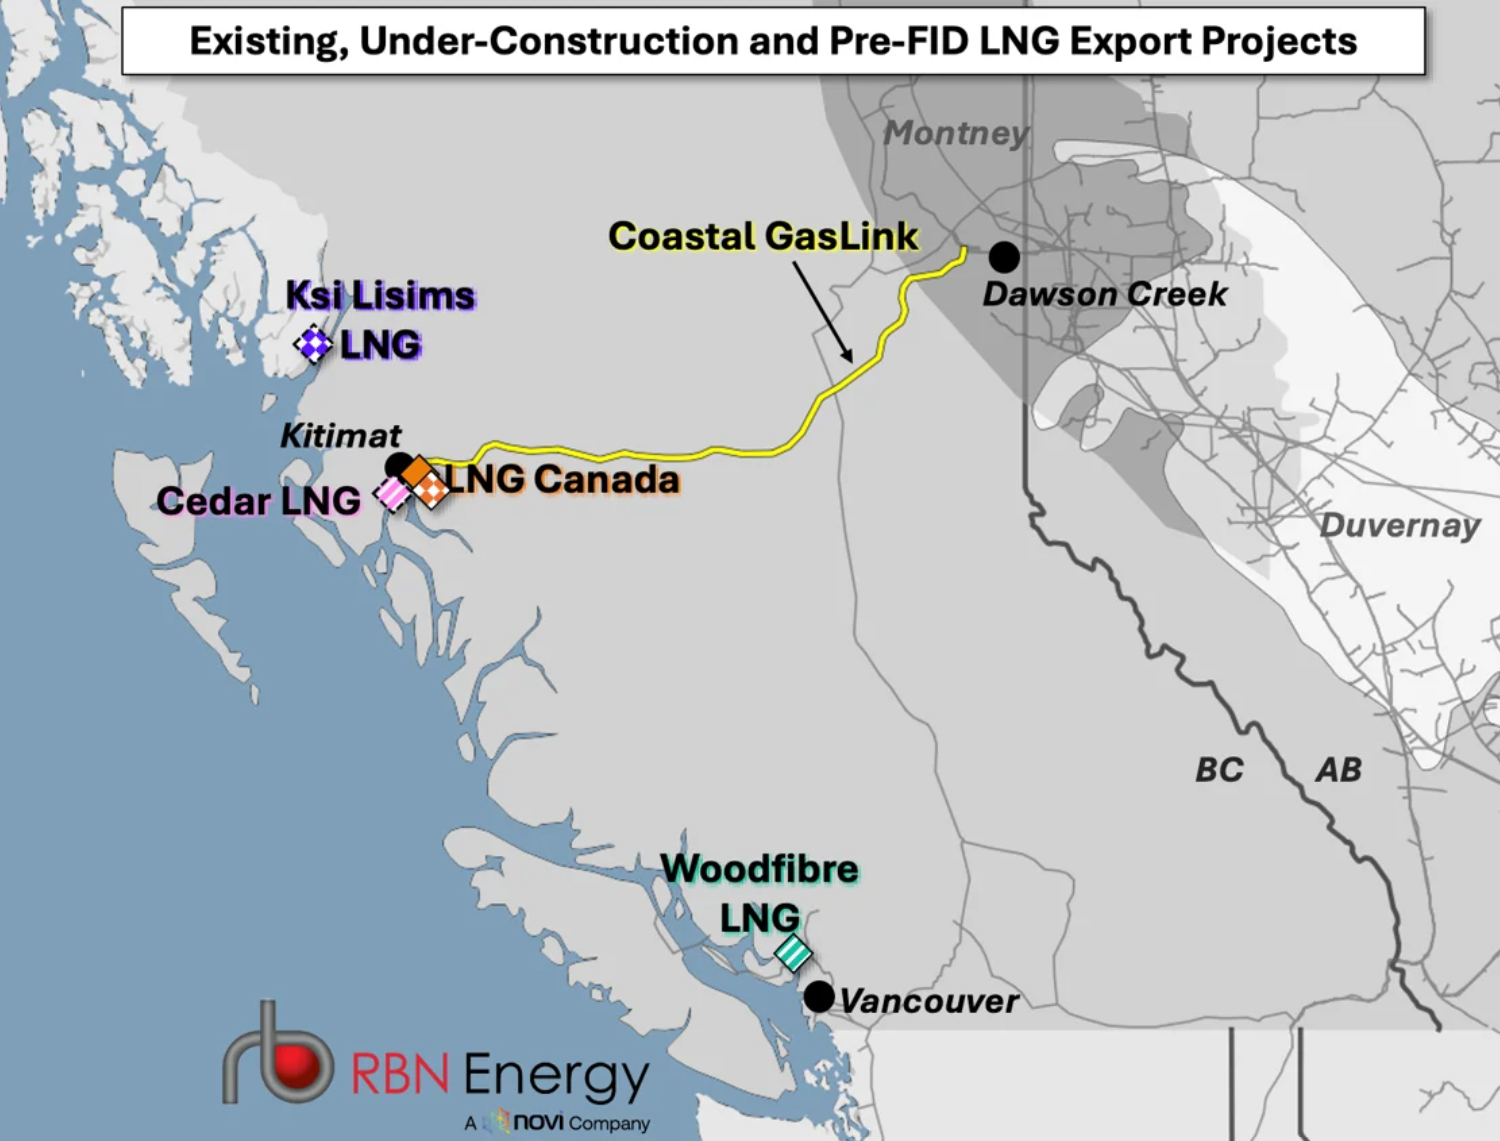
For a decade, the story of North American LNG has been written almost entirely along the Gulf Coast, where a flood of liquefaction capacity stretches from Corpus Christi to Plaquemines Parish. But for the important and growing Asian gas market, the Gulf Coast is a long way away. A cargo from Louisiana bound for Tokyo has to squeeze through the Panama Canal or take the long way around the Cape of Good Hope. That means a voyage of three weeks or more, versus roughly 10-12 days from British Columbia or Baja California. The tide of West Coast gas projects is rising and there has been a flurry of announcements in the last couple of weeks. The biggest came on September 29, when LNG Canada announced a positive final investment decision to proceed with Phase 2 (orange diamond in map below, for more, see our blog, Beautiful Day). The expansion doubles the Kitimat facility's production capacity from 14 MMtpa (~1.8 Bcf/d) to 28 MMtpa (~3.6 Bcf/d), with commercial operations expected to begin in the early 2030s. The JV's ownership tells you where the molecules are headed. Shell's partners include Malaysia's PETRONAS (25%), China's PetroChina (15%), Japan's Mitsubishi Corporation (15%), and South Korea's KOGAS (5%).
And a second wave is filling in behind LNG Canada. Woodfibre LNG near Squamish is a 2.1-MMtpa (~285 MMcf/d) facility targeting in-service in late 2027, and it was reported in April that the project is looking to double or triple in size (teal striped diamond). Cedar LNG, the Haisla/Pembina floating LNG project, remains on track for a late-2028 startup (pink striped diamond). Once fully operational, it would add roughly 3.3 MMtpa (~450 MMcf/d) of feed gas demand pulling on WCSB supply via Coastal GasLink (yellow line). Next up for FID is Ksi Lisims (purple checkered diamond). The floating LNG project north of Prince Rupert recently signed another tentative supply deal ahead of a final investment decision expected by the end of 2026, and it now has tentative sales deals for 9 MMtpa of its projected 12 MMtpa. We wrote a detailed update on the Canadian projects recently in Shut Up and Drive.
And the West Coast pull isn't limited to Canadian Montney supply. Permian gas is increasingly being plumbed toward Mexico's Pacific coast as well. As we will detail in an upcoming blog, on September 21, ESENTIA Energy Development agreed to acquire the Guadalajara-Manzanillo pipeline for $400 million from TC Energy. Esentia Energy’s pending acquisition of the Guadalajara-Manzanillo Pipeline, would give the company the last link in a chain of connecting pipelines that together — for the first time — would enable gas to flow along an integrated system from the Waha Hub to Mexico’s west coast. That matters because all or part of that expanded capacity could be employed by the proposed Gato Negro LNG project being planned by a group of investors led by Mexican entrepreneurs Carlos Camacho and Emilio Fuentes. The current plan calls for the project to be developed in three 3-MMtpa (400 MMcf/d) phases, with the first phase beginning commercial operation as soon as 2030-31 and the second and third phases following over the next two or three years.
Farther north in Baja, Sempra's ECA LNG has shown both the promise and the growing pains of being first. The inaugural cargo was lifted by TotalEnergies and shipped to Asia. However, a planned post-cargo inspection uncovered damage in the refrigerant compressors, which pushed substantial completion to 4Q26. Mexico Pacific's 15-MMtpa (2 Bcf/d) Saguaro project in Sonora remains the biggest Mexican wildcard. After missing its December 2025 export commencement deadline, the developer asked DOE to push commercial operations out to 2032.
Then there's Alaska, the longest-running "almost there" project in North American energy (see Road to Alaska). On September 30, President Trump announced that Alaska LNG would receive $54 billion from South Korea as part of an overall $200 billion investment agreement in U.S. energy infrastructure. That headline number covers nearly the whole project, since Glenfarne estimates the cost at up to $55 billion. But Seoul's framing was notably cooler. Korea's trade minister said the government is reviewing the project and will invest only if commercial viability is established. The commercial book is also not yet complete. Glenfarne holds preliminary, nonbinding agreements for 13 MMtpa across Asia, three million tons short of what it says it needs to finance the project. Still, the pitch is the same one driving every project on this list: proximity. Alaska avoids the Panama Canal entirely, and it gives Korean and Japanese buyers an energy-security hedge alongside a trade-policy relief valve.
Add it all up and the West Coast is a surging second front for North American LNG. On one side are Canadian and Alaskan supply basins getting increased access to a tidewater outlet. On the other is Permian gas taking the cross-border escape hatch through Mexico to reach the Pacific. The Gulf Coast will remain the volume king for years. But for Asian buyers counting days at sea, canal fees, and chokepoint risk, the marginal North American cargo is increasingly going to start its journey on the Pacific side of the continent.