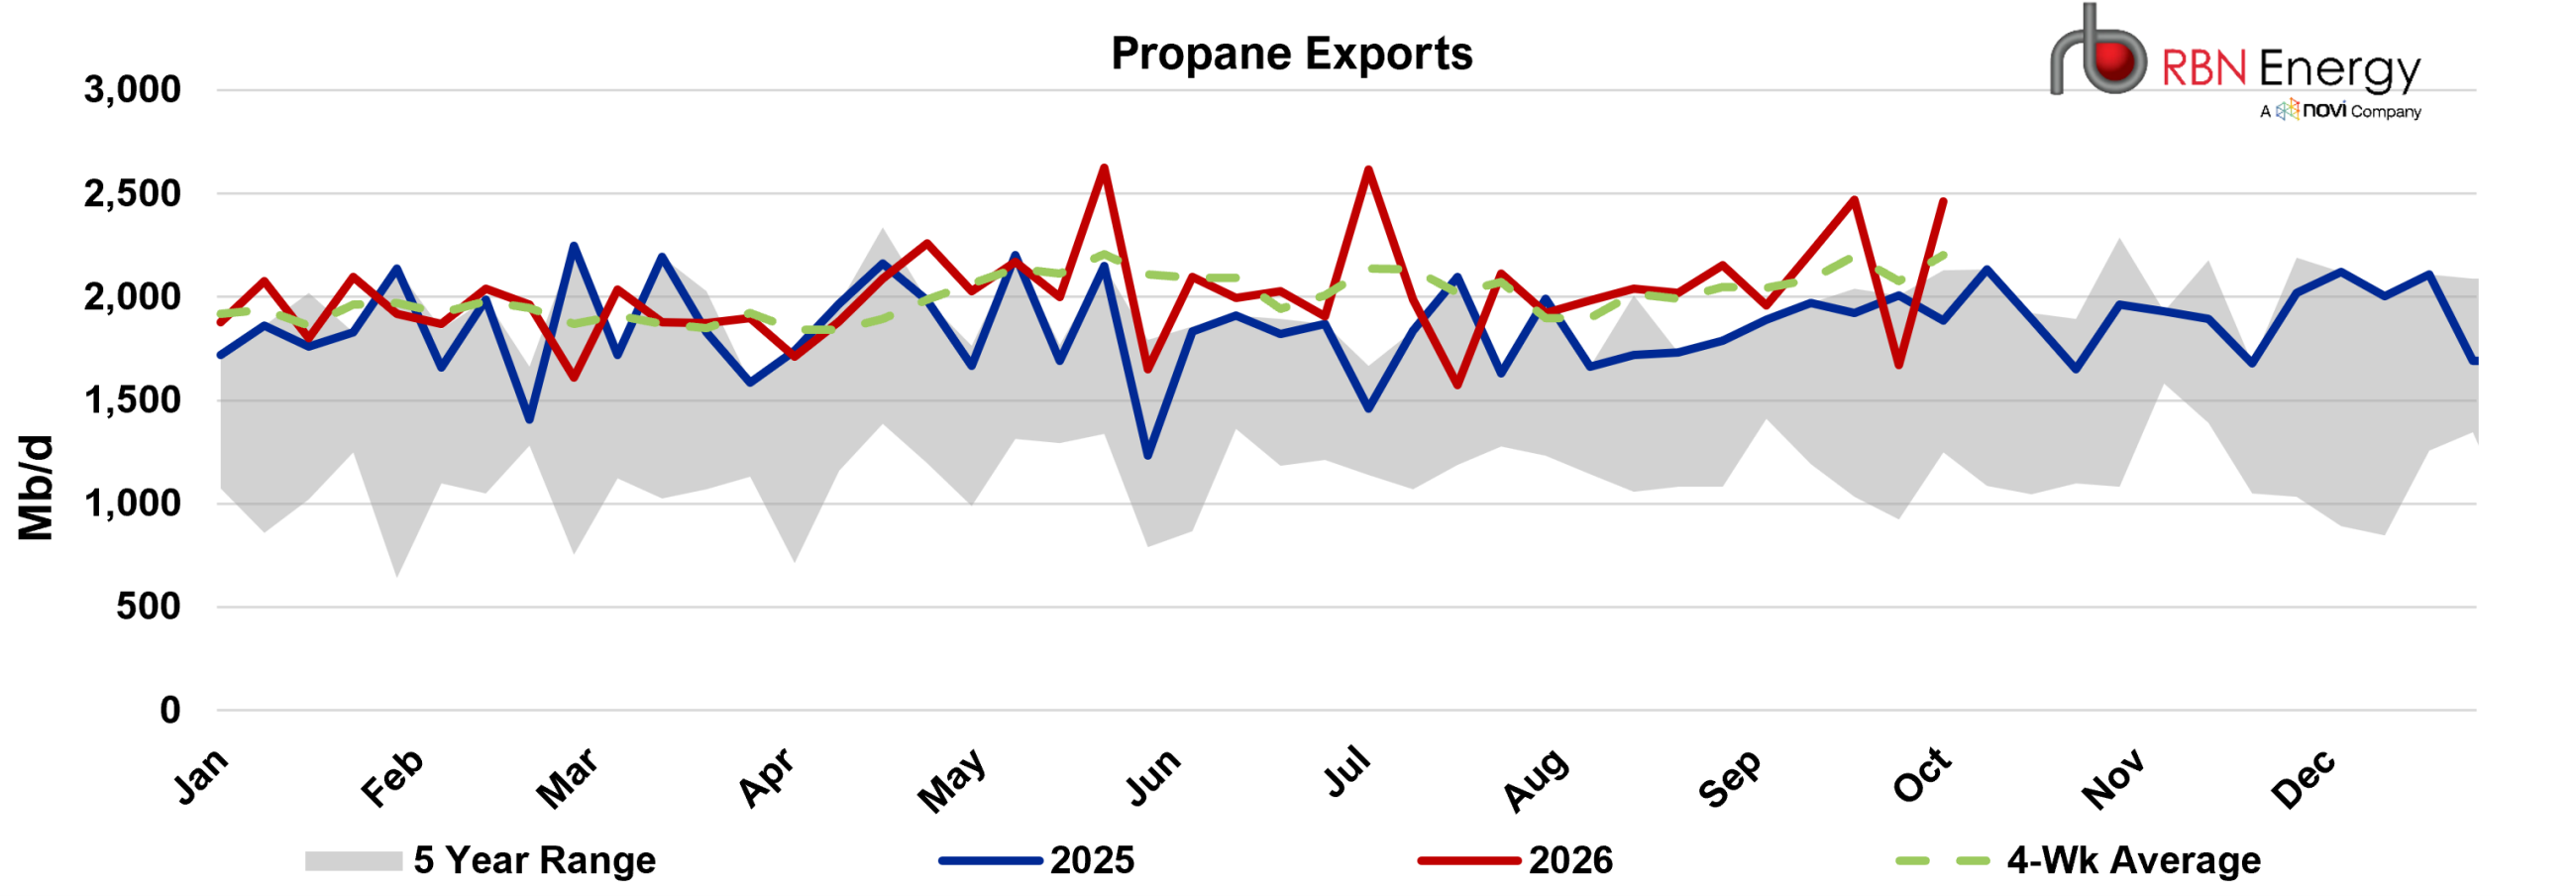
The EIA reported a 1.8-MMbbl draw in total U.S. propane/propylene inventories for the week ended October 2, lowering stocks to 107.8 MMbbl (red line in the chart below). The decline was well beyond industry expectations of a 467-Mbbl draw and ran counter to the average build of 128 Mbbl for the week, erasing the prior week's 1.8-MMbbl build. Even so, stocks are 7.3 MMbbl, or 7%, above the same week in 2025 (blue line), 6.3 MMbbl, or 6%, above the five-year maximum, and 15.9 MMbbl, or 17%, above the five-year average (green line).
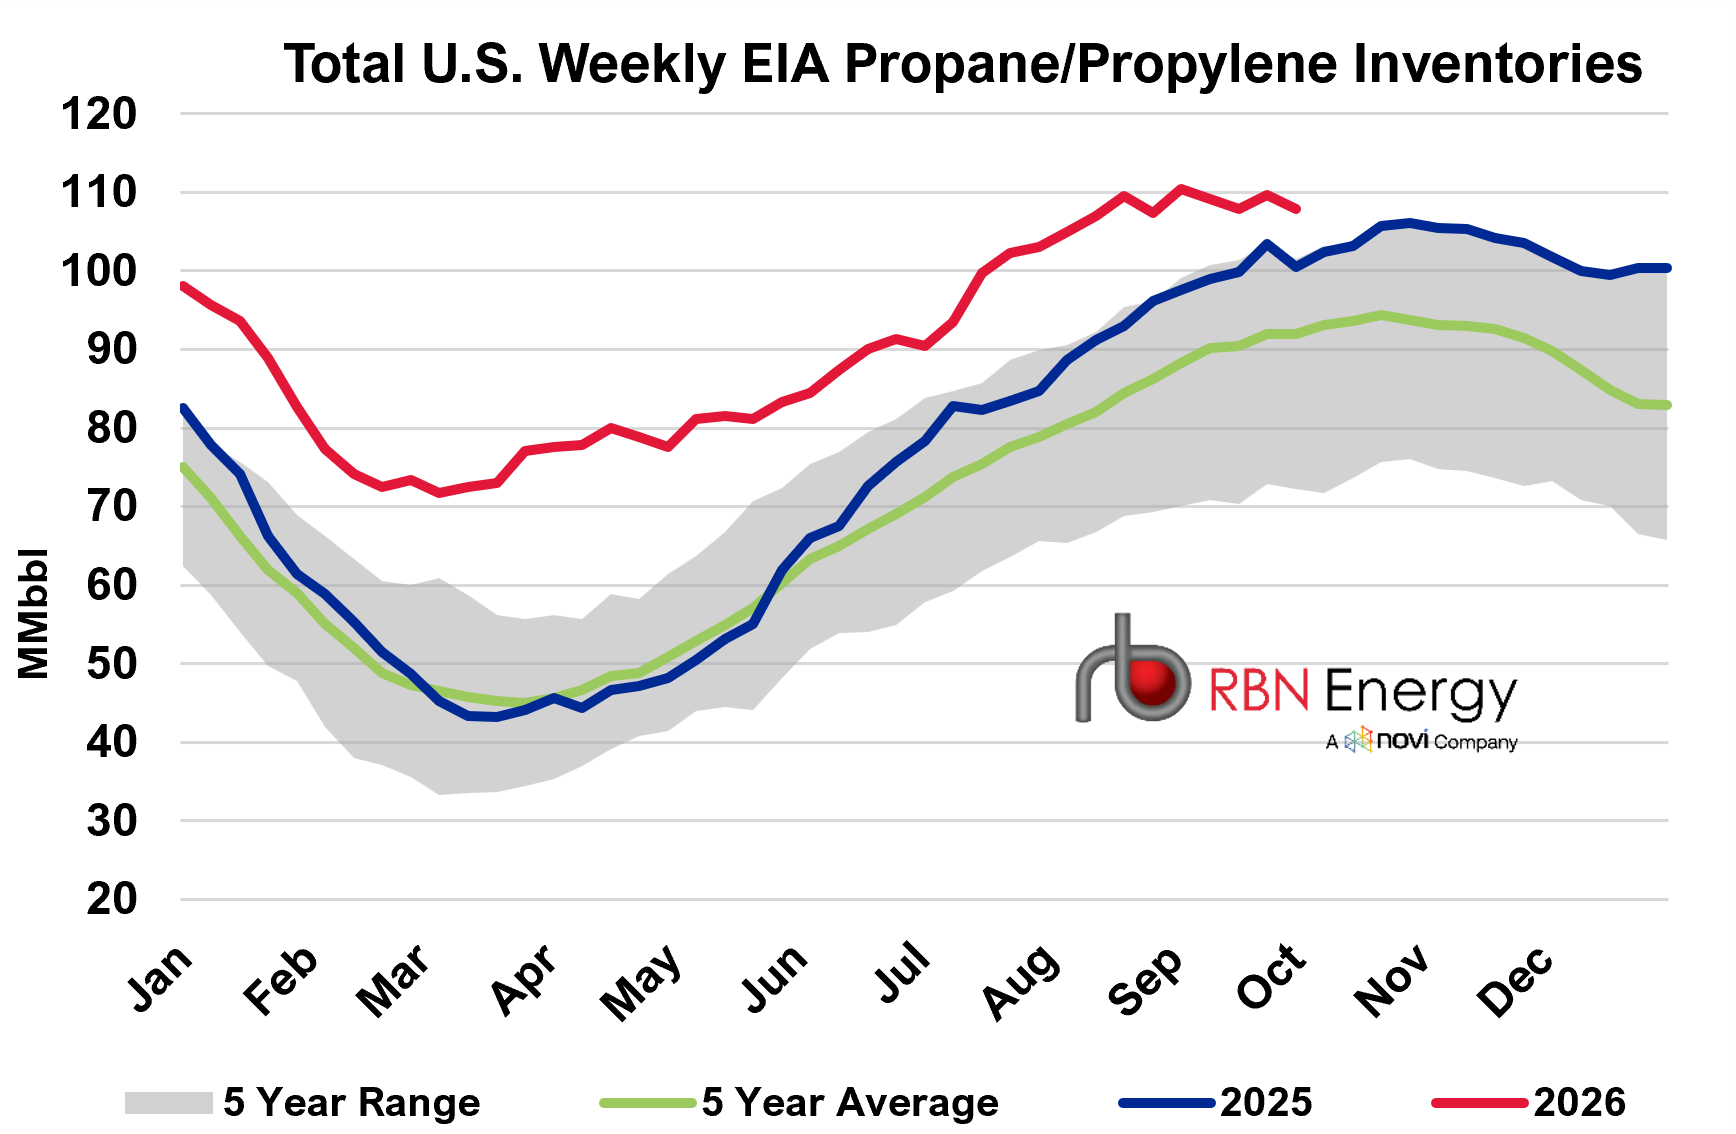
The draw was concentrated on the Gulf Coast, where PADD 3 inventories fell by 1.8 MMbbl to 68.7 MMbbl (red line in the chart below), down from the prior week’s record of 70.4 MMbbl. Changes elsewhere were small, as modest gains in the Midwest and East Coast were offset by a decline in PADDs 4 and 5. PADD 3 stocks nonetheless remain 8.5 MMbbl, or 14%, above both the same week in 2025 (blue line) and the previous five-year maximum, and 17.1 MMbbl, or 33%, above the five-year average (green line).
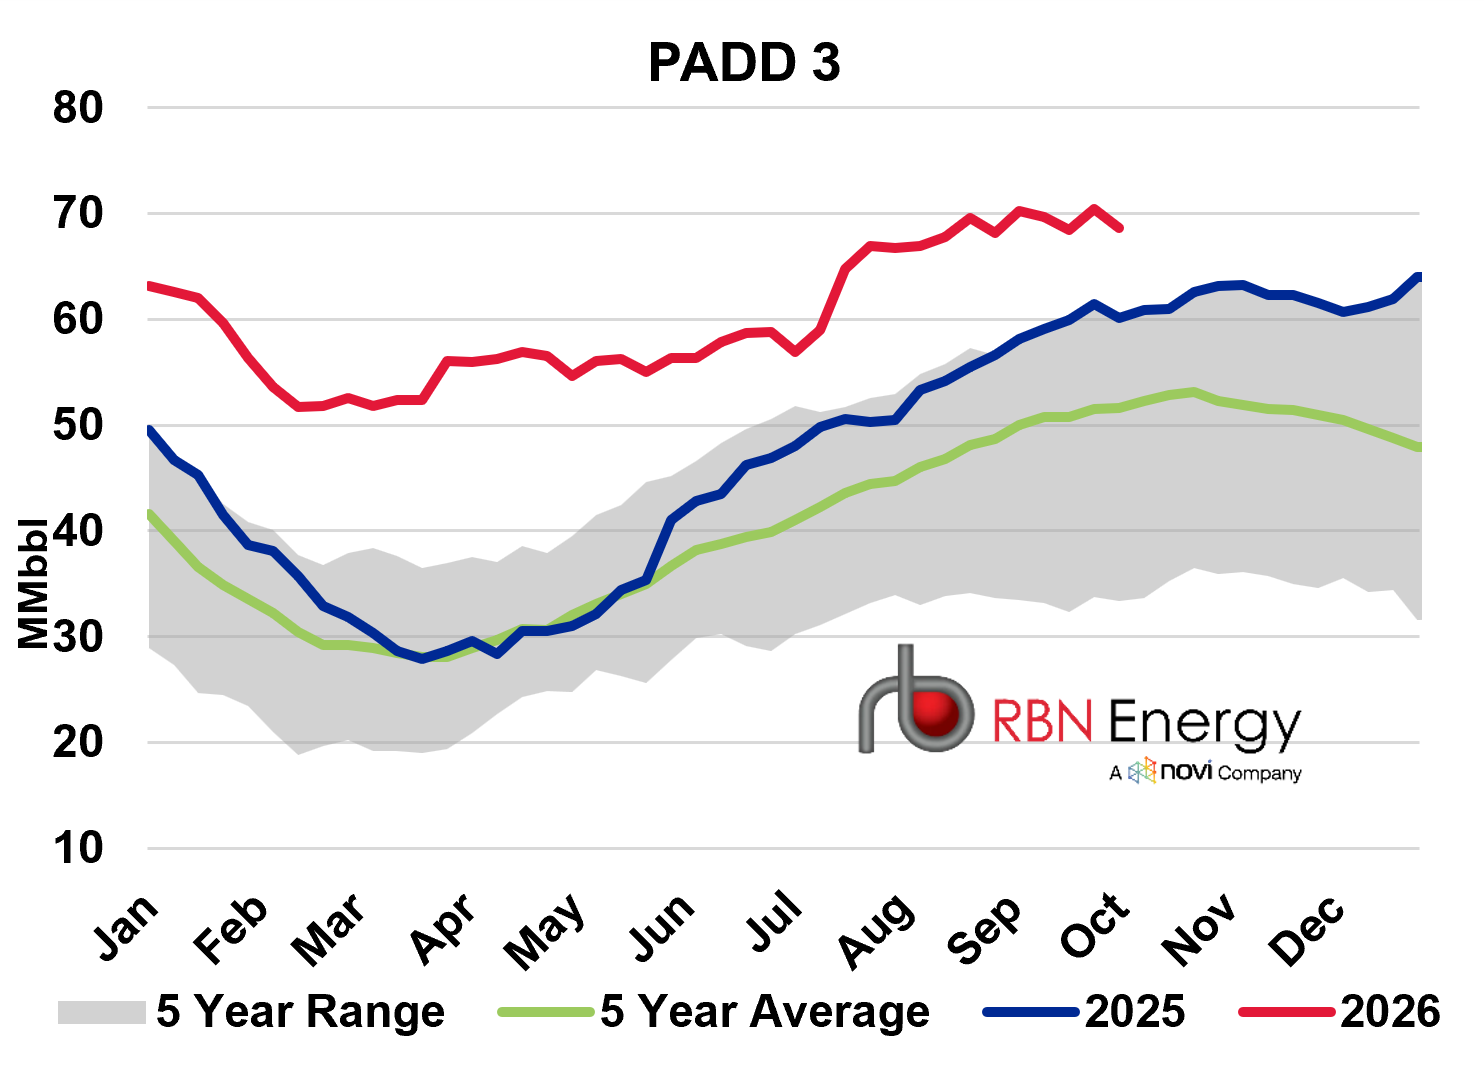
U.S. propane exports rebounded this week, increasing by 795 Mb/d to 2.46 MMb/d (red line in the chart below) and nearly reversing the prior week’s 800-Mb/d decline. Exports were 260 Mb/d, or 12%, above the four-week average of 2.2 MMb/d (green dashed line) and 579 Mb/d, or 31%, above the 1.89 MMb/d reported for the same week in 2025 (blue line). The increase coincided with a larger-than-expected draw in U.S. propane inventories, keeping the pace of exports in focus as the market moves into the seasonal draw period.