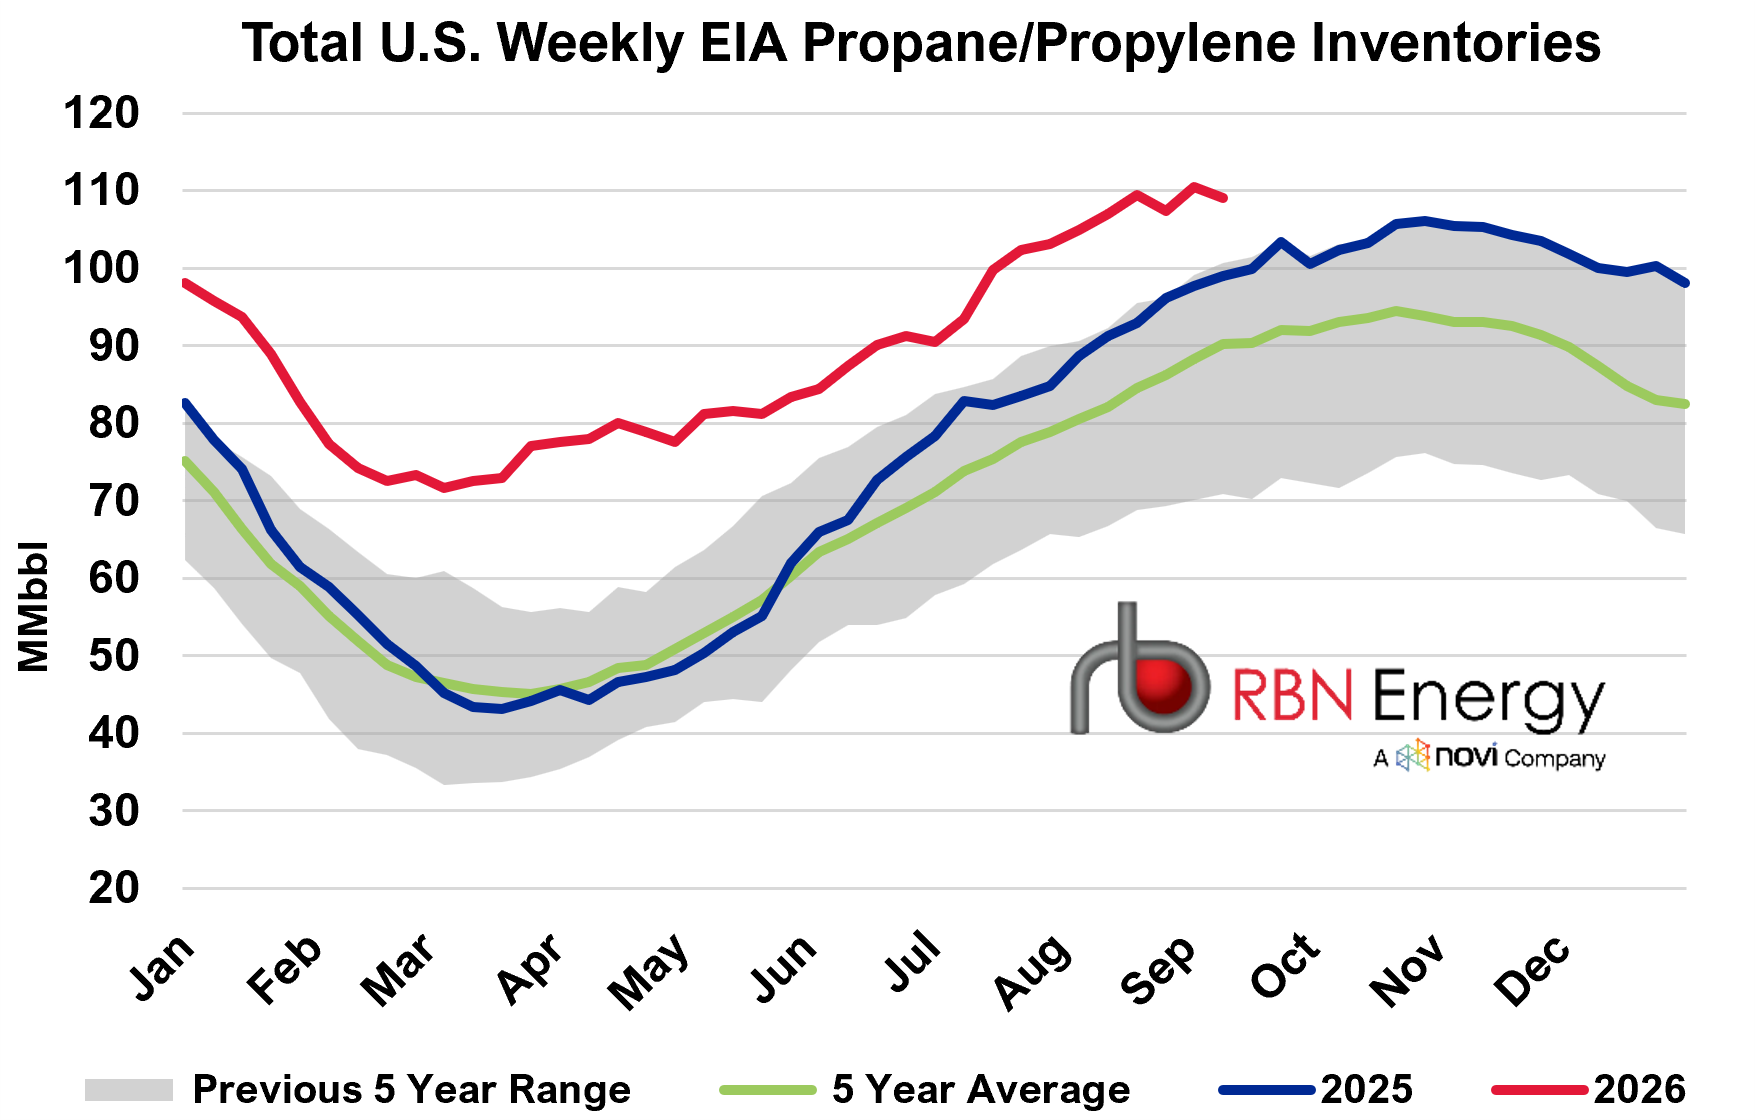
The EIA reported a 1.4-MMbbl decrease in total U.S. propane/propylene inventories for the week ended September 11, compared with an industry-expected build of 650 Mbbl and an average build of 1.0 MMbbl for the week. The counterseasonal draw—the largest for the comparable week in our records dating back to 2011—lowered stocks to 109.1 MMbbl (red line in the chart below). Despite the decline, inventories are 10.2 MMbbl, or 10%, above the same week in 2025; 8.4 MMbbl, or 8%, above the five-year maximum; and 18.9 MMbbl, or 21%, above the five-year average.
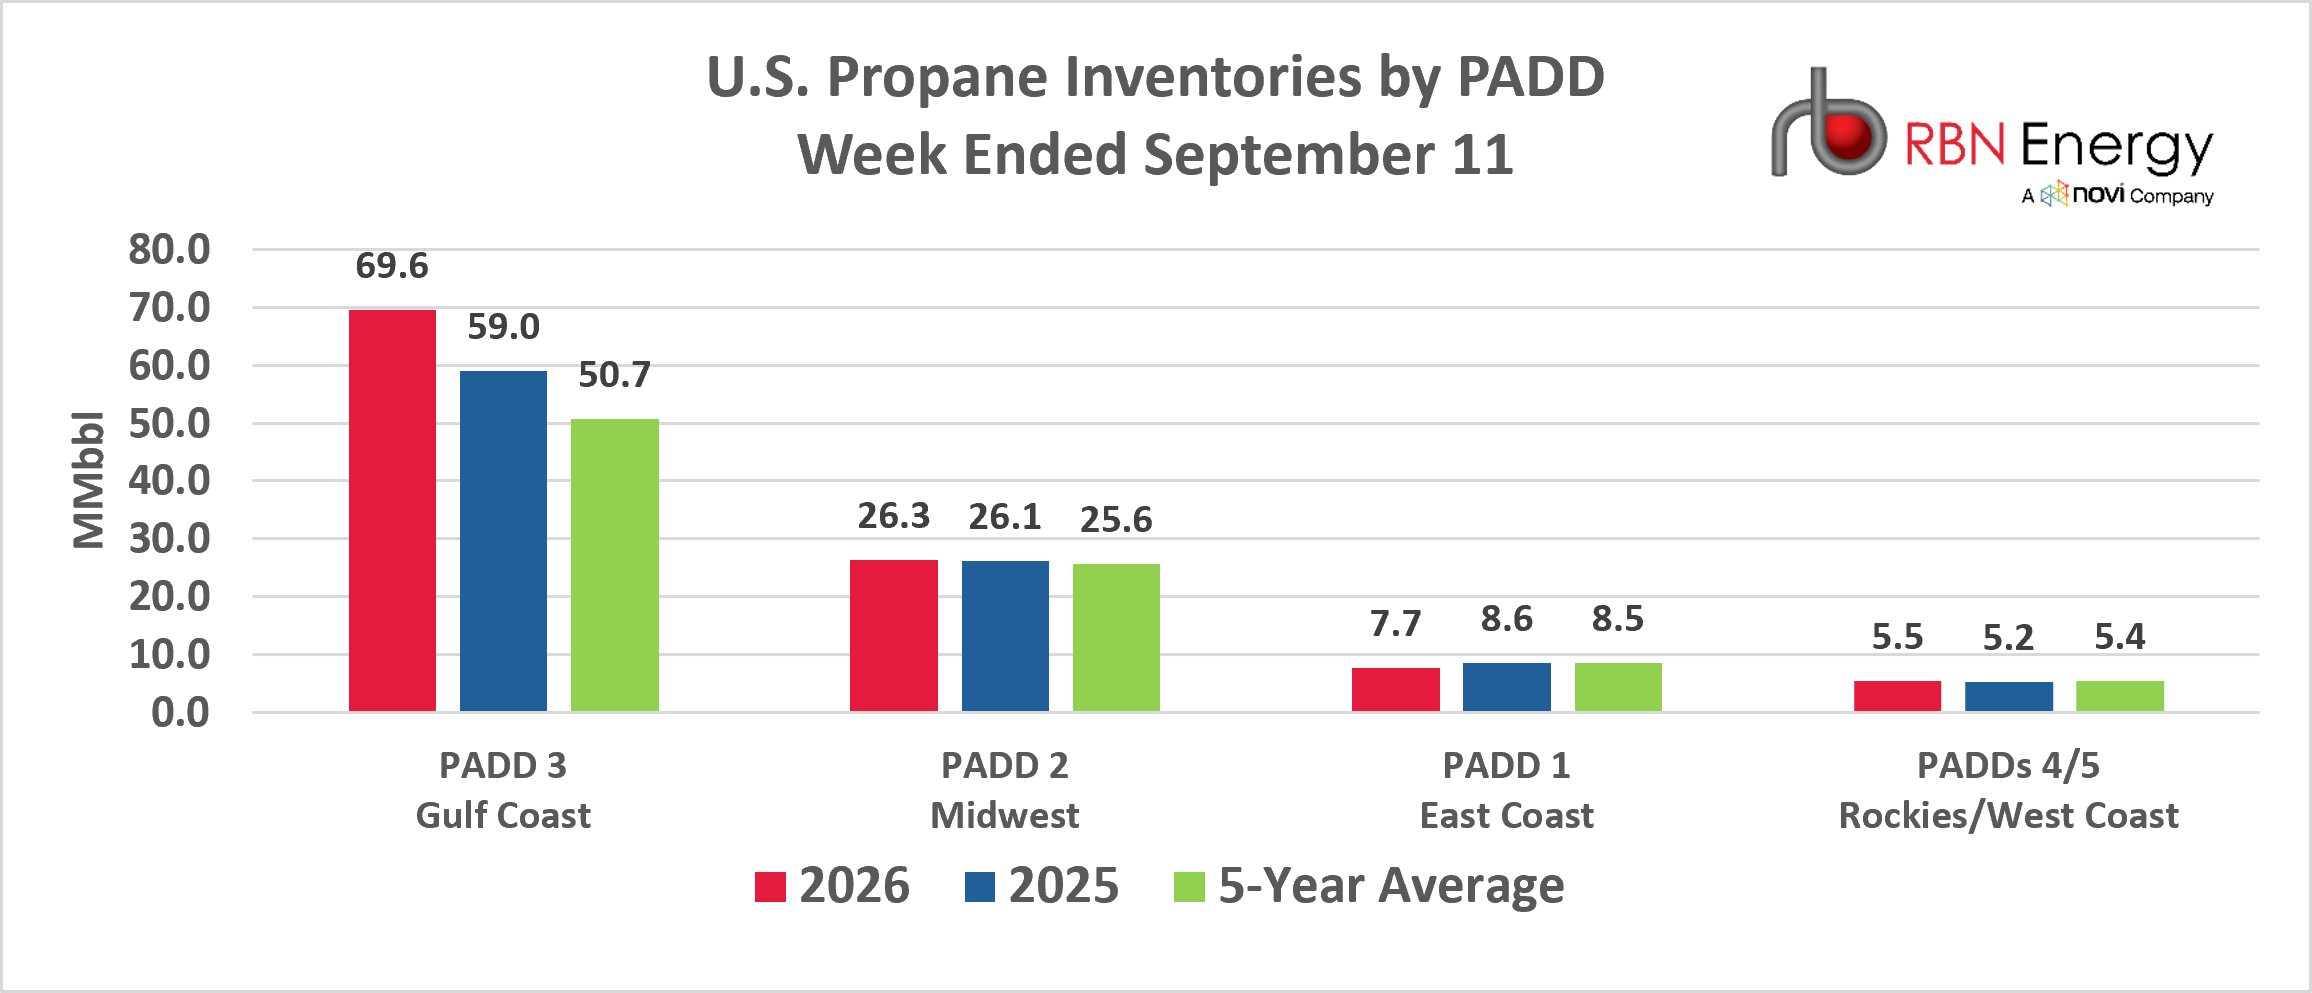
The draw was broad-based, led by a 781-Mbbl decline in PADD 1 (East Coast). Inventories in PADD 3 (Gulf Coast) and PADD 2 (Midwest) decreased by 570 Mbbl and 303 Mbbl, respectively, while a 277-Mbbl build in PADDs 4 and 5 provided a partial offset. As shown by the red bars in the chart below, inventories remain concentrated in PADD 3, where stocks are well above both the same week in 2025 and the five-year average. Although total stocks remain historically high, the counterseasonal draw reduced the additional inventory accumulated ahead of the winter heating season. Continued draws or below-normal builds over the next several weeks would narrow the current surplus and leave the market more exposed to strong winter demand.